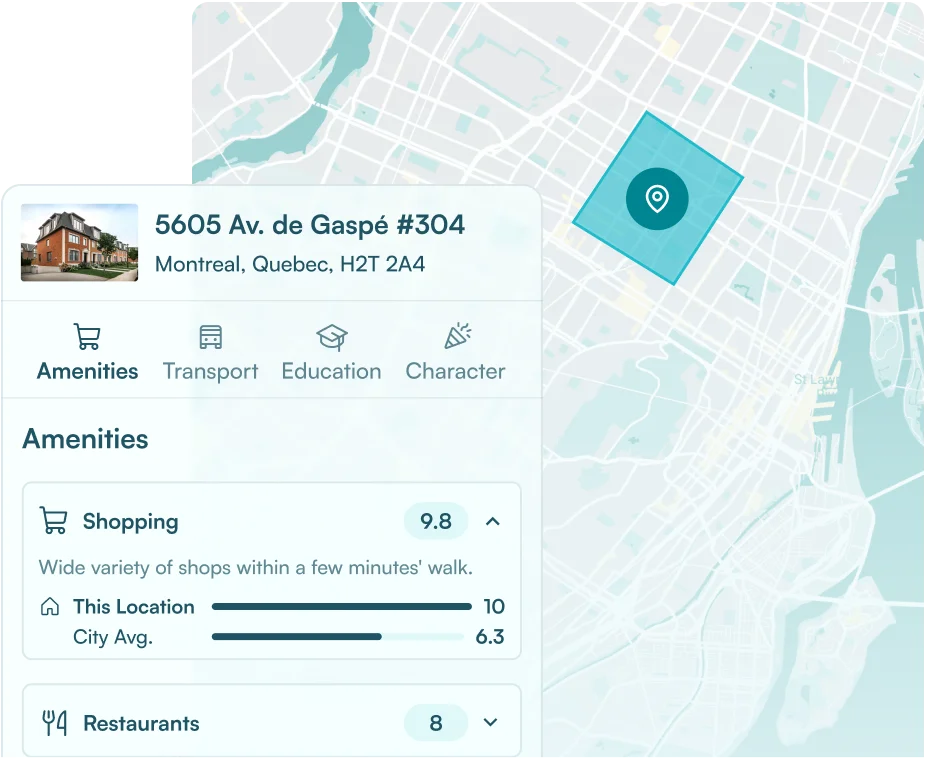


Ground your borrower and loan-officer tools on the Local Logic MCP for accurate, current, objective market and location context. Measured attributes only, with no crime data and no protected-class fields.
Why grounded location context for lending is a worthy use case
Lenders increasingly put AI in front of borrowers and loan officers, in pre-approval tools, neighborhood guides, and renewal nurture. The moment those tools describe a place or a local market, accuracy becomes a compliance and trust issue, not just a nice-to-have. A generic model will state a median price, a market condition, or a neighborhood detail with total confidence and no way to tell whether it is real. In lending, a confident wrong number is a liability.
The Local Logic MCP grounds those answers in measured, objective market data. It gives your AI verified location and market context on demand, drawn from calibrated data rather than the model memory, and it is built for this setting: measured attributes only, with no crime data and no protected-class fields, so the location layer stays on the right side of fair-lending boundaries by design.
What good looks like
Every market figure and neighborhood detail in a borrower-facing tool is measured and current, and the data layer contains only objective attributes suitable for business use.
How to build it
- Connect the MCP to your borrower toolsPoint your pre-approval assistant, neighborhood guide, or renewal nurture flow at the hosted MCP with your MCP key. It works through the OpenAI and Anthropic APIs and any MCP-compatible client.
- Resolve the marketCall
search_geographiesto turn a city or neighborhood into a stablegeog_idso every figure refers to the same area. - Pull objective market and location dataCall
get_market_statsfor prices, pace, and conditions,get_demographicsfor objective household and income context, andget_scoresfor lifestyle context. - Keep it compliant and currentAnswer from returned values only, present an honest gap where there is no data, and rely on measured attributes only, with no protected-class fields feeding any decision.
- Reuse it across the funnelThe same connection powers pre-approval, education, and renewal touchpoints, so borrowers get consistent, accurate context at every stage.
See it in action
A lender neighborhood guide is asked about Frisco, Texas, for a relocating borrower. Here is the generic answer versus the same model grounded on the Local Logic MCP. Every grounded figure is a live response.
Behind the scenes: MCP tool calls
✗ Generic model, ungrounded
“Frisco homes typically sell for around $500,000, and the market is extremely hot with bidding wars. Expect homes to sell in a few days.”
The median is well off, and the market characterization is a guess that contradicts current conditions.
✓ Grounded on Local Logic MCP
“In Frisco, single-family homes have a median sold price of $675K at about $232 per square foot, selling in a median 16 days in what is currently a neutral market. The area is about 69% owner-occupied with a median household income near $134K.”
Objective, current, and defensible.
The market at a glance
| Metric (single-family, trailing 12 months) | Frisco, TX |
|---|---|
| Median sold price | $675,000 |
| Median price per square foot | $232 |
| Median days on market | 16 (fast) |
| Market condition | Neutral |
| Median household income | $134,210 |
| Owner-occupied | 69% |
The payoff
Grounded location context lets lenders build borrower experiences that are genuinely helpful without taking on the risk of invented numbers. The AI speaks with accuracy about local markets, the underlying data stays objective and compliant, and one connection serves the whole borrower journey from first search to renewal.
Frequently asked questions
Why does lending need grounded location data?
Borrower-facing AI often states prices, market conditions, and neighborhood details. Grounding them in measured data keeps those answers accurate and defensible rather than confidently wrong.
Is the data fair-lending safe?
The MCP exposes measured attributes only, with no crime data and no protected-class fields, so the location layer stays within fair-lending boundaries by design. Demographics are objective market data for business use.
How current is the market data?
Market statistics are updated daily, so prices, pace, and conditions reflect the current market rather than a stale snapshot.
Which tools does it use?
search_geographies to resolve the market, then get_market_stats for prices and pace, get_demographics for objective context, and get_scores for lifestyle context.
Where can we use it?
Anywhere you put AI in front of borrowers or loan officers, including pre-approval tools, neighborhood guides, and renewal nurture, through any MCP-compatible client or the OpenAI and Anthropic APIs.
Ground this use case on your own market
Bring us your query mix. We will show you the grounded difference live, on the neighborhoods you care about.
At a glance
- Best forMortgage & Lending
- WhoMortgage & lending digital teams
- CoverageUS & Canada
- SetupOne URL + MCP key
MCP tools used
search_geographies
get_market_stats
get_demographics
get_scores